Can An Indexed Universal Life Policy Beat The Market?
Welcome to the exciting world of finance, where we get to ask a truly fun question: Can an Indexed Universal Life (IUL) policy actually beat the stock market? It’s like pittin...
Welcome to the exciting world of finance, where we get to ask a truly fun question: Can an Indexed Universal Life (IUL) policy actually beat the stock market? It’s like pitting a safety-conscious marathon runner against a Formula 1 car. This topic is helpful because it challenges the idea that you must choose between protection for your family and growth for your money. The purpose of an IUL is to offer a compromise—a way to chase market-like returns without the terrifying roller-coaster ride.
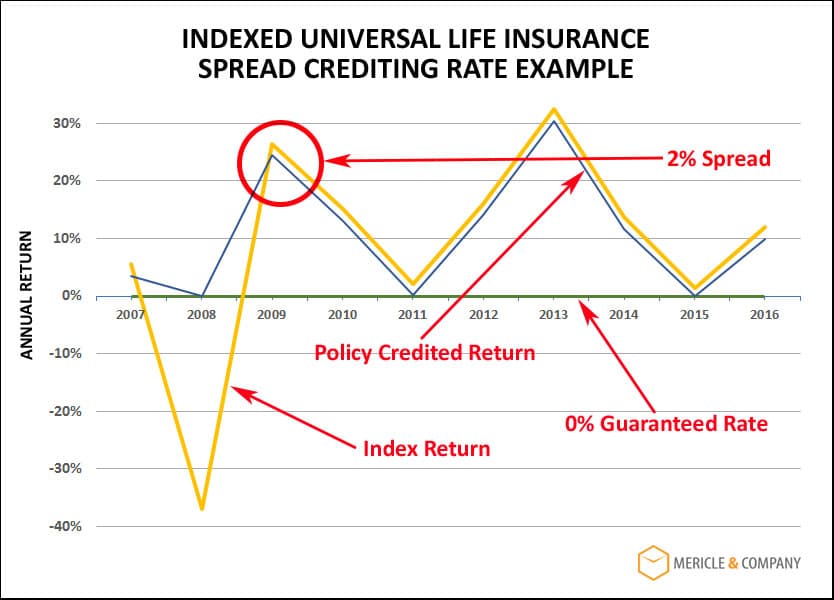
The first advantage is the floor on losses. While the S&P 500 can drop 20% in a bad year, an IUL typically guarantees you won’t lose money if the index goes down. Think of it as having a financial airbag. However, the catch is a cap on gains. If the market roars up 30%, your policy might only credit you 10% or 12%. So, can it beat the market? In a bull run, no. But in a flat or down year, it wins big by simply not losing.
Let’s paint a creative example. Imagine you’re investing $10,000. Year one, the market crashes 15%—you lose $1,500. But your IUL credits zero loss. You keep the full $10,000. Year two, the market jumps 25%—but your IUL caps at 10%. So you gain $1,000 on the IUL, while the market is at $12,500. Over five years of such zig-zags, the compounding effect of avoiding losses can make the IUL competitive, even if it never “beats” a peak year.
Must Read
Here’s a secret: IULs shine brightest when you add tax advantages. You can take policy loans tax-free in retirement, which the stock market (in a taxable account) cannot match. So, even if the market’s raw returns are higher, your after-tax pocket money from an IUL might be better. For example, a 7% average market return after taxes might equal a 6% IUL return with zero taxes. Suddenly, the gap shrinks dramatically.
 Indexation in Life Insurance: How Do You Index Link a Policy?
Now, practical advice for the curious. Don’t dump your 401(k) for an IUL. Instead, treat it as a supplement for the “safe bucket” of your portfolio. Look for policies with low caps but high participation rates—like 100% participation with a 10% cap is better than 50% participation with a 15% cap. And always check the cost of insurance; younger, healthier people win big here.
Your golden tip: ask the agent to run a “worst-case” scenario—what if the market stays flat for a decade? A good IUL should still break even or grow slightly. If it doesn’t, walk away. Also, never buy one if you need the money in less than 10 years—it’s a long-term friend, not a quick-date investment. So, can an IUL beat the market? Only in a game where avoiding losses matters more than winning big. And that, my friend, is a very smart game to play.
